
소득공제
수입
직수입양서
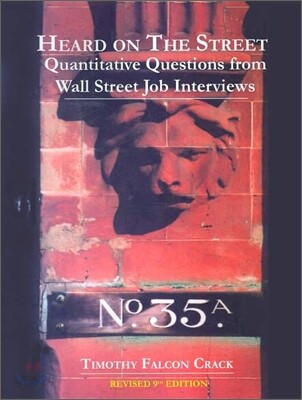
Heard on the Street: Quantitative Questions from Wall Street Job Interviews
Paperback, 9th Edition
Timothy F. Crack
Timothy Crack
2003.12.01.
이미 소장하고 있다면 판매해 보세요.
- 국내배송만 가능
- 해외 거래처 사정에 의하여 품절/지연 가능
- 도서 정보 중 미표기 사항 안내?
- 문화비소득공제 가능
책소개
목차
|
1 Introduction 1
2 Purely Quantitative & Logic Questions 7 3 Derivatives Questions 21 4 Other Financial Economics Questions 35 5 Statistics and Programming Questions 41 5.1 Statistics Questions 41 5.2 Programming Questions 47 6 Non-Quantitative Questions 49 6.1 Questions about You 50 6.2 Questions about Your Job Awareness 54 6.3 Questions about the Markets or the Economy 56 6.4 Financial Management Questions 57 6.5 Thinking Questions 58 A Purely Quantitative & Logic Answers 61 B Derivatives Answers 119 C Other Financial Economics Answers 193 D Statistics Answers 215 E Non-Quantitative Answers (Selected) 237 F Basic Option Pricing Theory 243 F.1 Logarithms and Exponentials 243 F.2 Normality and Lognormality 248 F.3 Prices, Returns and Compounding 253 F.4 Option Pricing 258 F.4.1 A Discussion of the Black-Scholes Formula 265 F.5 Deriving the Black-Scholes Formula 268 F.5.1 A Derivation of the Black-Scholes Formula 268 F.5.2 Discussion of the Derivation 272 G HP 17B and 19B Source Code 275 G.1 Black-Scholes Call and Put Prices 275 G.2 Binomial Option Pricing 279 G.3 Macaulay Duration 281 G.4 Macaulay Convexity 281 References for Further Research 285 Index 303 |
품목정보
- 발행일
- 2003년 12월 01일
- 쪽수, 무게, 크기
- 284쪽 | 644g | 210*280*10mm
- ISBN13
- 9780970055231
사락 별점0
혜택 및 유의사항밑줄0
혜택 및 유의사항상품정보안내
직수입외서의 경우, 해외거래처에서 제공하는 정보가 부족하여 제목, 표지, 가격, 유통상태 등의 정보가 미비하거나 변경되는 경우가 있습니다. 정확한 확인을 원하시는 경우, 일대일 상담으로 문의하여 주시면 답변 드리겠습니다.
(판형과 판수 등이 다양한 도서는 찾으시는 도서의 ISBN을 알려 주시면 보다 빠르고 정확한 안내가 가능합니다.)
해외거래처에서 품절인 경우, 2차 거래선을 통해 유럽과 미국 출판사로 직접 수입이 진행될 수 있습니다.
수입 진행 시점으로 부터 2~3주가 추가로 소요되며, 해외에서도 유통이 원활하지 않은 도서는 품절 안내가 지연될 수 있습니다.
해당 경우, 문자와 메일로 별도 안내를 드리고 있사오니 마이페이지에서 휴대전화번호와 메일주소를 다시 한번 확인해주시기 바랍니다.
(판형과 판수 등이 다양한 도서는 찾으시는 도서의 ISBN을 알려 주시면 보다 빠르고 정확한 안내가 가능합니다.)
해외거래처에서 품절인 경우, 2차 거래선을 통해 유럽과 미국 출판사로 직접 수입이 진행될 수 있습니다.
수입 진행 시점으로 부터 2~3주가 추가로 소요되며, 해외에서도 유통이 원활하지 않은 도서는 품절 안내가 지연될 수 있습니다.
해당 경우, 문자와 메일로 별도 안내를 드리고 있사오니 마이페이지에서 휴대전화번호와 메일주소를 다시 한번 확인해주시기 바랍니다.
