
이미 소장하고 있다면 판매해 보세요.
- 국내배송만 가능
- 문화비소득공제 가능
책소개
목차
|
PREFACE xi
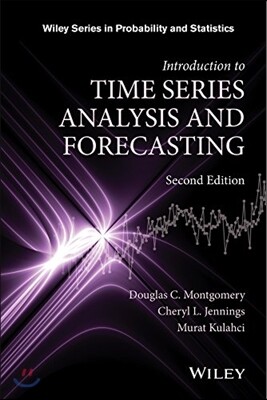
1 INTRODUCTION TO FORECASTING 1 1.1 The Nature and Uses of Forecasts 1 1.2 Some Examples of Time Series 6 1.3 The Forecasting Process 13 1.4 Data for Forecasting 16 1.5 Resources for Forecasting 19 2 STATISTICS BACKGROUND FOR FORECASTING 25 2.1 Introduction 25 2.2 Graphical Displays 26 2.3 Numerical Description of Time Series Data 33 2.4 Use of Data Transformations and Adjustments 46 2.5 General Approach to Time Series Modeling and Forecasting 61 2.6 Evaluating and Monitoring Forecasting Model Performance 64 2.7 R Commands for Chapter 2 84 3 REGRESSION ANALYSIS AND FORECASTING 107 3.1 Introduction 107 3.2 Least Squares Estimation in Linear Regression Models 110 3.3 Statistical Inference in Linear Regression 119 3.4 Prediction of New Observations 134 3.5 Model Adequacy Checking 136 3.6 Variable Selection Methods in Regression 146 3.7 Generalized and Weighted Least Squares 152 3.8 Regression Models for General Time Series Data 177 3.9 Econometric Models 205 3.10 R Commands for Chapter 3 209 4 EXPONENTIAL SMOOTHING METHODS 233 4.1 Introduction 233 4.2 First-Order Exponential Smoothing 239 4.3 Modeling Time Series Data 245 4.4 Second-Order Exponential Smoothing 247 4.5 Higher-Order Exponential Smoothing 257 4.6 Forecasting 259 4.7 Exponential Smoothing for Seasonal Data 277 4.8 Exponential Smoothing of Biosurveillance Data 286 4.9 Exponential Smoothers and Arima Models 299 4.10 R Commands for Chapter 4 300 5 AUTOREGRESSIVE INTEGRATED MOVING AVERAGE (ARIMA) MODELS 327 5.1 Introduction 327 5.2 Linear Models for Stationary Time Series 328 5.2.1 Stationarity 329 5.2.2 Stationary Time Series 329 5.3 Finite Order Moving Average Processes 333 5.4 Finite Order Autoregressive Processes 337 5.5 Mixed Autoregressive-Moving Average Processes 354 5.6 Nonstationary Processes 363 5.7 Time Series Model Building 367 5.8 Forecasting Arima Processes 378 5.9 Seasonal Processes 383 5.10 Arima Modeling of Biosurveillance Data 393 5.11 Final Comments 399 5.12 R Commands for Chapter 5 401 6 TRANSFER FUNCTIONS AND INTERVENTION MODELS 427 6.1 Introduction 427 6.2 Transfer Function Models 428 6.3 Transfer Function-Noise Models 436 6.4 Cross-Correlation Function 436 6.5 Model Specification 438 6.6 Forecasting with Transfer Function-Noise Models 456 6.7 Intervention Analysis 462 6.8 R Commands for Chapter 6 473 7 SURVEY OF OTHER FORECASTING METHODS 493 7.1 Multivariate Time Series Models and Forecasting 493 7.3 Arch and Garch Models 507 7.4 Direct Forecasting of Percentiles 512 7.5 Combining Forecasts to Improve Prediction Performance 518 7.6 Aggregation and Disaggregation of Forecasts 522 7.7 Neural Networks and Forecasting 526 7.8 Spectral Analysis 529 7.9 Bayesian Methods in Forecasting 535 7.10 Some Comments on Practical Implementation and Use of Statistical Forecasting Procedures 542 7.11 R Commands for Chapter 7 545 APPENDIX A STATISTICAL TABLES 561 APPENDIX B DATA SETS FOR EXERCISES 581 APPENDIX C INTRODUCTION TO R 627 BIBLIOGRAPHY 631 INDEX 639 |
품목정보
- 발행일
- 2015년 05월 04일
- 쪽수, 무게, 크기
- 672쪽 | 163*241*41mm
- ISBN13
- 9781118745113
리뷰/한줄평0
상품정보안내
직수입외서의 경우, 해외거래처에서 제공하는 정보가 부족하여 제목, 표지, 가격, 유통상태 등의 정보가 미비하거나 변경되는 경우가 있습니다. 정확한 확인을 원하시는 경우, 일대일 상담으로 문의하여 주시면 답변 드리겠습니다.
(판형과 판수 등이 다양한 도서는 찾으시는 도서의 ISBN을 알려 주시면 보다 빠르고 정확한 안내가 가능합니다.)
해외거래처에서 품절인 경우, 2차 거래선을 통해 유럽과 미국 출판사로 직접 수입이 진행될 수 있습니다.
수입 진행 시점으로 부터 2~3주가 추가로 소요되며, 해외에서도 유통이 원활하지 않은 도서는 품절 안내가 지연될 수 있습니다.
해당 경우, 문자와 메일로 별도 안내를 드리고 있사오니 마이페이지에서 휴대전화번호와 메일주소를 다시 한번 확인해주시기 바랍니다.
(판형과 판수 등이 다양한 도서는 찾으시는 도서의 ISBN을 알려 주시면 보다 빠르고 정확한 안내가 가능합니다.)
해외거래처에서 품절인 경우, 2차 거래선을 통해 유럽과 미국 출판사로 직접 수입이 진행될 수 있습니다.
수입 진행 시점으로 부터 2~3주가 추가로 소요되며, 해외에서도 유통이 원활하지 않은 도서는 품절 안내가 지연될 수 있습니다.
해당 경우, 문자와 메일로 별도 안내를 드리고 있사오니 마이페이지에서 휴대전화번호와 메일주소를 다시 한번 확인해주시기 바랍니다.
